Latest Update: November 2026
This article reflects federal mortgage interest rules applicable to the 2026 tax year, including changes enacted under the One Big Beautiful Bill Act (OBBBA). It also explains how mortgage points are treated across home purchases, refinancing transactions, rental properties, and business-owned real estate.
Answer Snippet
Yes, mortgage points are tax deductible, but you must itemize your deductions to claim them. The IRS treats discount points as prepaid mortgage interest, so they fall under the home mortgage interest deduction guidelines.
Key Facts at a Glance
One mortgage point generally equals 1% of the loan amount.
Discount points are treated as prepaid interest when they meet IRS requirements.
Qualifying points on a primary residence may be deducted immediately.
Points on refinanced mortgages and second homes generally require amortization.
Seller-paid points may qualify for a buyer deduction, subject to a basis adjustment.
Personal mortgage interest deductions generally require itemizing on Schedule A.
The general acquisition debt limit for qualifying post-December 15, 2017, mortgages is $750,000, or $375,000 for married taxpayers filing separately.
Quick Read
Not every mortgage closing charge qualifies as a deductible point.
Discount points and lender service fees receive different tax treatment.
Primary residence purchases may qualify for an immediate deduction.
Refinancing and second-home transactions generally require amortization.
Rental and commercial property financing involves separate tax considerations.
Proper documentation helps prevent incorrect deductions and reporting inconsistencies.
Introduction
Mortgage closing costs can significantly increase the amount a borrower needs to pay when purchasing property. Among these expenses, mortgage points deserve particular attention because they influence both borrowing costs and potential tax deductions.
For homeowners, understanding whether mortgage points tax deductible payments qualify for an immediate deduction can affect annual tax planning. Property investors and business owners face additional considerations involving loan purpose, property classification, and financing-cost accounting.
The distinction is important. Claiming a deduction too early can create compliance issues, while overlooking an eligible expense may result in a higher tax liability than necessary.
Understanding Mortgage Points and Their Tax Treatment
Mortgage points are upfront payments made to a lender to obtain a mortgage or secure a lower interest rate. One point generally equals 1% of the loan principal. For example, one point on a $400,000 mortgage costs $4,000.
Discount Points Versus Origination Fees:
Discount points are prepaid interest payments made to reduce the mortgage interest rate. They can lower monthly payments and overall borrowing costs, depending on how long the borrower retains the mortgage. Origination fees, on the other hand, may cover underwriting, processing, documentation, or other administrative services. These charges do not automatically qualify as interest deductions.
Charges That Do Not Qualify:
Appraisal fees, notary charges, mortgage insurance premiums, and mortgage note preparation costs cannot simply be classified as deductible points. Borrowers should review the Closing Disclosure carefully to distinguish qualifying interest from service-related charges.
When Mortgage Points Qualify for an Immediate Deduction
The IRS permits a full deduction in the year paid when the mortgage and payment satisfy specific requirements. Generally, the loan must be secured by the taxpayer’s principal residence and used to purchase or construct that home.
The IRS Conditions for a Same-Year Deduction: The main requirements include:
- Paying points must be an established local lending practice.
- The amount charged must not exceed customary local rates.
- The borrower must use the cash method of accounting.
- Points must not replace separately stated service charges.
- The borrower must provide sufficient funds at or before closing without borrowing the funds from the lender or mortgage broker.
- Points must be calculated as a percentage of the loan principal and clearly identified in the closing documents
Qualifying points paid on a loan to substantially improve the principal residence may also qualify for immediate deduction if the applicable conditions are met.
Seller-Paid Points and the Property Basis Adjustment:
When a seller pays qualifying mortgage points on behalf of a buyer, the buyer is generally treated as having paid them. However, the buyer must reduce the property’s tax basis by the seller-paid amount. The seller treats the payment as a selling expense rather than deductible mortgage interest.
When Mortgage Points Qualify for an Immediate Deduction
When a transaction does not qualify for an immediate deduction, points generally need to be spread over the mortgage term. This process is known as amortization.
Refinancing and Second Homes:
Points paid when refinancing an existing mortgage generally cannot be deducted in full during the year of refinancing. Instead, qualifying amounts are usually amortized over the new loan's term. An exception applies when part of the refinancing proceeds is used to substantially improve the principal residence. The qualifying portion of points attributable to those improvements may be deducted immediately. Second-home mortgages also generally require amortization rather than a full deduction in the year paid.
What Happens When You Pay Off or Refinance Early?
If a mortgage is paid off or the property is sold before the end of the loan term, the remaining eligible unamortized points may generally be deducted in that year. However, when the borrower refinances with the same lender, the remaining balance generally continues to be amortized over the new loan term rather than being deducted immediately.
When Mortgage Points Qualify for an Immediate Deduction
Property type | General tax treatment |
|---|---|
Primary residence | Immediate deduction may be available if IRS conditions are met. |
Second home | Generally amortized over the mortgage term. |
Rental property | Generally recognized over the applicable loan period, subject to tax rules. |
Business-owned property | Requires treatment based on the loan purpose, applicable tax rules, and accounting standards. |
The property’s classification determines which deduction rules apply. A homeowner claiming personal mortgage interest cannot automatically use the same treatment as a property investor or business owner.
Calculating the Deduction: A Practical Example
Consider a homeowner who takes a $300,000 mortgage and pays $6,000 in qualifying points. Assume the points must be amortized over a 30-year loan term.
- Total points: $6,000
- Mortgage duration: 360 months
- Monthly amortization: $16.67
- Annual deduction for 12 full months: approximately $200
The homeowner may generally deduct approximately $200 annually, subject to the applicable mortgage interest limitations.
This illustrates how tax-deductible mortgage points are recognized over time rather than automatically claimed as a single closing-year expense.
Calculating the Deduction: A Practical Example
For qualifying mortgage debt incurred after December 15, 2017, the general home acquisition debt limit is $750,000 for married couples filing jointly and $375,000 for married individuals filing separately. Older qualifying debt may remain subject to the previous $1 million and $500,000 limits.
The limits apply to combined qualifying mortgage debt on a taxpayer’s main and second homes. When the mortgage exceeds the applicable threshold, the deductible interest must be calculated using the IRS limitation rules. Consequently, otherwise qualifying points may also be subject to a deduction limitation.
The OBBBA, enacted in July 2025, made the lower mortgage debt limits permanent for qualifying post-2017 loans.
Are Mortgage Points Deductible for Business or Rental Property?
The tax treatment of mortgage points changes when the property generates rental income or is used for business purposes. In these cases, the purpose of the borrowing and how the proceeds are used become important considerations.
Rental and Investment Property:
Points associated with rental properties are generally treated as financing costs or prepaid interest and recognized over the applicable loan period under the relevant tax rules. Property owners managing multiple rental units should maintain separate loan-cost schedules to avoid mixing financing expenses with regular operating costs. If a property is refinanced, the allocation of points may also depend on how the additional loan proceeds are used.
Business-Owned and Entity-Held Property:
When a corporation, partnership, or LLC finances commercial property, the treatment depends on the borrowing arrangement, entity classification, and use of the proceeds. Interest-related charges may require amortization, while other financing fees may have different capitalization or deduction requirements. Business owners should also distinguish between personally owned property used for business and property held directly by a separate legal entity. The reporting treatment can differ depending on the ownership and tax structure.
Tax Versus Book Treatment of Loan Costs:
Financial accounting and tax reporting do not always follow identical rules. Under applicable accounting standards, qualifying debt issuance costs are generally presented as a reduction of the related debt liability and amortized using the effective interest method. Tax reporting may require a separate calculation. Maintaining distinct book and tax schedules helps accounting teams reconcile differences and support accurate financial statements.
Which Tax Treatment Applies? Four Common Scenarios
Scenario | General approach |
|---|---|
Primary home purchase | Test eligibility for an immediate deduction under IRS rules. |
Mortgage refinancing | Generally amortize points over the new loan term, subject to applicable exceptions. |
Rental property purchase | Apply the relevant financing-cost and interest allocation rules. |
LLC-owned commercial building | Review loan purpose, entity tax status, and financing-cost treatment. |
These scenarios demonstrate why points on a mortgage tax deductible questions require more than a review of the closing statement. The borrower’s circumstances and the property’s use determine the appropriate treatment.
Which Tax Treatment Applies? Four Common Scenarios
A tax deduction should not be the only reason to purchase mortgage points. Borrowers should compare the upfront payment with the expected interest savings over the period they plan to retain the mortgage. For example, assume a borrower pays $4,000 in points and saves $55 each month through a lower interest rate.
The break-even period is:
$4,000 ÷ $55 = approximately 73 months.
The borrower needs to retain the mortgage for roughly six years and one month before the monthly savings recover the initial payment. The decision should also consider available cash, refinancing possibilities, and the actual interest-rate reduction offered by the lender. A potential tax deduction for mortgage points may improve the overall economics, but it does not automatically make purchasing points worthwhile.
A Five-Step Checklist Before Filing
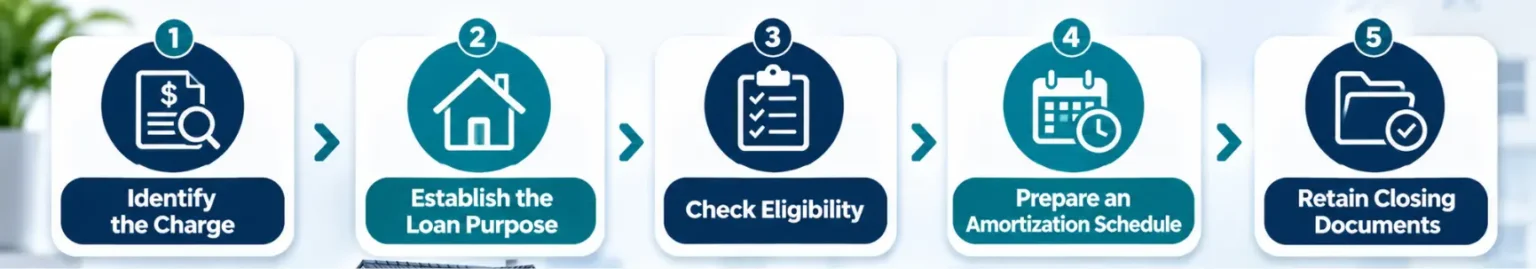
Before claiming a deduction, review these five areas:
- Identify the charge: Confirm that the payment represents qualifying discount points rather than administrative fees.
- Establish the loan purpose: Determine whether the property is a primary residence, second home, rental, or commercial property.
- Check eligibility: Review IRS requirements, applicable debt limits, and itemization rules.
- Prepare an amortization schedule: Record the original payment, loan term, deductions already claimed, and remaining balance.
- Retain closing documents: Keep the Closing Disclosure, Form 1098, mortgage agreement, and supporting payment records.
A consistent documentation process makes it easier to verify deductions and respond to questions during tax preparation or an IRS examination.
How Fresnel Partners Helps
Mortgage financing creates accounting and tax reporting responsibilities that extend beyond recording monthly loan payments. Businesses and property investors need reliable records of interest expenses, financing charges, loan balances, and amortization schedules.
Fresnel Partners supports businesses with accounting, financial reporting, and tax-related processes. This includes assistance with financing transaction records, expense reconciliation, loan-cost schedules, and period-end reporting.
For organizations managing multiple properties or financing arrangements, consistent documentation improves visibility into borrowing costs and helps distinguish deductible expenses from costs requiring capitalization or further tax review.
Conclusion
Mortgage points can provide a meaningful tax benefit, but the timing and amount of the deduction depend on the loan purpose, property use, and applicable IRS requirements.
Homeowners should establish whether an immediate deduction is available, while investors and business owners should pay particular attention to amortization and financing-cost records. Getting the classification right before filing can help prevent reporting errors and support better financial decisions.
Frequently Asked Questions About Business Property Taxes
Yes. Qualifying points may be deductible in 2026, subject to IRS requirements. Points paid on an eligible principal residence may qualify for a full deduction in the year paid, while refinancing and second-home points generally require amortization. Personal mortgage interest deductions usually require itemizing on Schedule A and complying with applicable mortgage debt limits.
The mortgage generally must be secured by your principal residence and used to purchase or construct that home. The points must reflect customary local lending practices, be reasonable in amount, and be properly documented. You must also meet the IRS requirements concerning funds provided at closing and the treatment of other charges. Certain qualifying home improvement loans may also qualify.
Individuals generally report deductible personal mortgage points as mortgage interest on Schedule A of Form 1040. Reconcile the amount with Form 1098 and your closing documents. Amortized points may require separate calculations. Rental and business property financing expenses follow different reporting rules and should not automatically be reported as personal itemized deductions.
Yes. Under Section 70108 of the One Big Beautiful Bill Act, qualifying mortgage insurance premiums are again treated as qualified residence interest for tax years beginning after December 31, 2025. The deduction is subject to applicable mortgage debt limits, income-based phaseout provisions, and other eligibility requirements. This treatment is separate from the rules governing discount points.
Generally, yes, if the points relate to your personal residence. Personal mortgage points treated as qualified residence interest are included among itemized deductions. Taxpayers who claim the standard deduction generally cannot claim a separate personal mortgage points deduction. Rental and business property financing expenses, however, follow separate tax rules and may be deductible independently of personal itemization.
What’s Next?
Mortgage financing costs deserve careful attention, particularly when a business or property portfolio involves multiple loans and reporting requirements. Incorrect expense classification or incomplete amortization records can affect financial statements and tax filings.
Fresnel Partners helps businesses maintain organized accounting records, monitor financing expenses, and support accurate financial reporting. If your organization needs assistance with loan-cost accounting, expense reconciliation, or broader financial management processes, connect with Fresnel Partners to discuss your requirements.
Author Profile
- Paul Clough, CPA
- At Fresnel Partners, Paul Clough works to increase the power and focus of entrepreneurial businesses for their executives and owners. He does this by providing planning, operational, and management development advisory services that enable clients to solve problems, realize opportunities, and manage their businesses more effectively. Paul is a CPA and provides tax planning and compliance services for individuals and business owners. Before starting his business in 2009, Paul held corporate executive positions in several industries including cable television technology, subscription consumer services, and outsourced business services. After early career work in finance, Paul’s management responsibilities were in sales and marketing roles where he conceptualized, planned, and launched several business units. Paul earned an MBA from Harvard University and a BS in Accounting from Bucknell University. He is active in his local community, having served as the President of the Youth Orchestra of Bucks County and Board Chair for the Lower Bucks County Chamber of Commerce.
- November 11, 2026AccountingAre Mortgage Points Tax Deductible? What Homeowners and Business Owners Should Know
- October 27, 2026UncategorizedConstruction Job Costing: How to Track Costs and Protect Profit Margins
- September 23, 2026UncategorizedClient Accounting Services (CAS): How CPA Firms Manage a Company’s Full Financial Operations
- September 9, 2026UncategorizedWhat Is FP&A (Financial Planning and Analysis)? A Practical Guide